
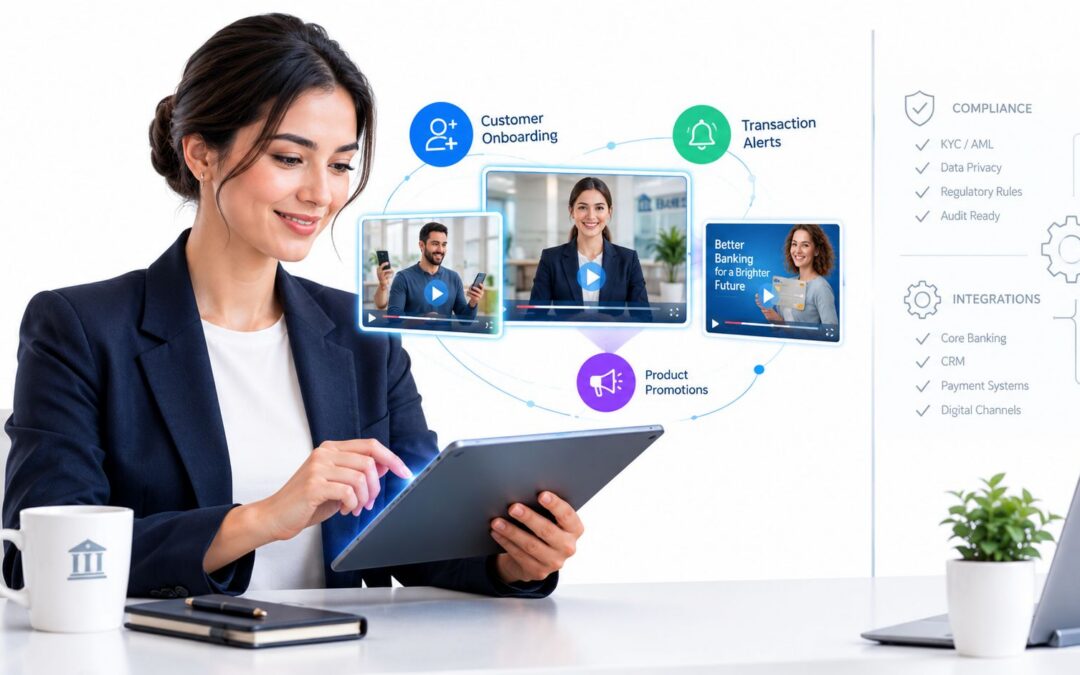
Video automation for banks turns static account statements into data-driven, one-to-one customer updates. Instead of asking people to skim a generic PDF, a bank can automatically render a short audiovisual piece using approved account information, relevant activity, and eligible offers.
Replace Static Statements With Video Automation for Banks
A retail bank might connect its core system, CRM, and product database to a governed template. Each customer’s name, account type, current balance, notable transaction activity, and product eligibility becomes a controlled variable. The template then produces a clear account summary, while the bank sends it through email, its mobile app, or a secure notification.
The shift is simple: from paperwork customers skim to a recorded message designed around what matters to them.
Picture a quarterly statement email that says only, “Your document is ready.” A customer may miss a recurring fee, overlook savings progress, or fail to notice eligibility for a lower-cost product. A context-aware summary can explain those points in a few focused scenes, with labels, narration, and calls to action that remain consistent across every account.
For example, a retail bank could send a monthly update saying, “Maria, here’s your checking account summary,” then show her account type, recent spending category, balance trend, and an approved savings offer. A different customer might receive a mortgage-related update, with only the fields permitted for that segment.
The workflow supports practical outcomes across banking:
- Customer clarity: account activity becomes easier to understand.
- Retention: timely, relevant communication gives customers a reason to return.
- Sales enablement: eligible offers appear beside useful financial context.
- Operational efficiency: teams create one template instead of editing thousands of statements.
- Internal reporting: managers can review delivery, viewing, and response data.
The model also fits the wider banking move toward data-led operations, as research on automation in banks explains. Yet banking communication requires tighter controls than ordinary marketing. Compliance teams can approve the script, scenes, disclosures, branding, and fixed fields before release, while the system accepts only validated values from authorised sources.
A bank could begin with quarterly summaries, test completion rates and support contacts, then expand to onboarding, transaction alerts, product promotions, and staff training. Teams that need account data to flow into a governed template, trigger rendering after a reporting event, and distribute the result through approved channels can explore Wideo’s video automation platform.
When customers can see the meaning behind their numbers, a statement becomes a service conversation rather than another forgotten document.
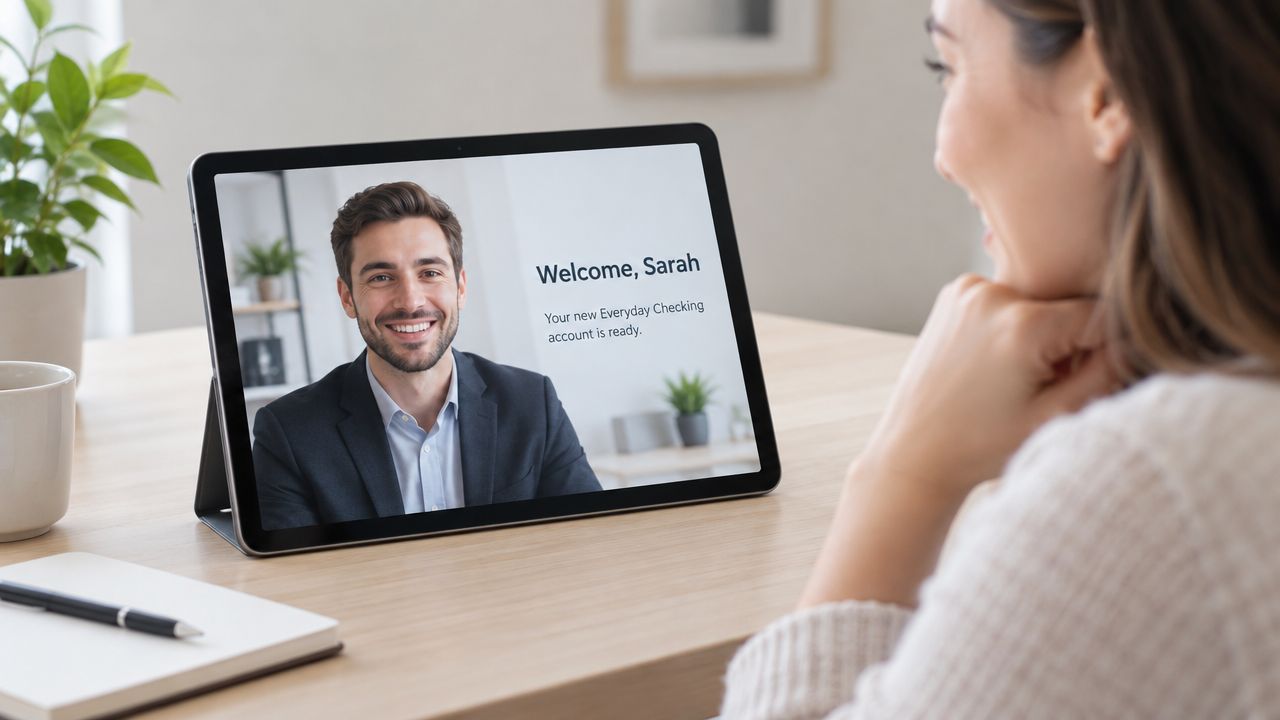
Opening a bank account can feel like stepping into a maze of paperwork, verification codes, and features nobody bothers to explain. That’s exactly the friction point where video automation for banks makes a measurable difference. Rather than firing off a bland welcome email, a bank can generate a short, context-aware video that actually references the customer’s specific account details.
Picture this: a retail bank connects its core banking system and CRM to an approved video template. That template pulls in the customer’s name, account type, opening date, available digital tools, and the single most relevant next action. Everything gets assembled into a coherent welcome message without anyone touching an editing tool.
The real shift is moving from explaining every account identically to showing each customer what actually matters for theirs.
Crafting a Welcome Message That Does the Work
Let’s say Jordan just opened a checking account. The video greets Jordan by name, confirms the account type, walks through mobile deposit, and highlights the steps to set up transaction alerts. Meanwhile, a customer who opened a savings account sees a completely different version — one focused on setting up automatic transfers, tracking savings goals, and whether they qualify for a specific savings feature.
This approach shrinks the gap between what the bank’s systems know and what the customer understands. Service teams start getting fewer repetitive “how do I do X?” calls. Relationship managers, on the other hand, find a natural opening to introduce relevant products at a moment when the customer is actually paying attention.
The data fields banks typically map into these templates include:
- Customer identity: name and preferred greeting style.
- Account context: checking, savings, loan, or card type.
- Relevant activity: a recent deposit, transfer, or completed setup step.
- Next action: activate a card, verify identity, or turn on notifications.
- Eligible offer: a product pre-approved for that customer segment only.
Think of a governed template as a marked-up form rather than a blank script. Compliance teams approve the wording, disclosures, visuals, and allowed data fields once. After that, the system pulls validated values from authorized sources and nothing else.
That control is essential. Banking communications have to stay accurate, traceable, and consistent across every touchpoint. Teams can review the data feed, template version, delivery event, and customer response — building a full audit trail without anyone needing to inspect each video individually.
For hands-on advice about building context-aware messages like these, check out this guide to personalized video creation.
A sensible rollout starts with the welcome sequence. Measure completion rates and incoming support contacts from there, then expand into transaction alerts, product education, and staff training. Once the data source, template, trigger, and distribution channel are working in sync, onboarding stops being a one-off campaign and becomes a repeatable service process.
The strongest first impression isn’t a slick animation. It’s a clear message that helps a new customer actually take their next step.
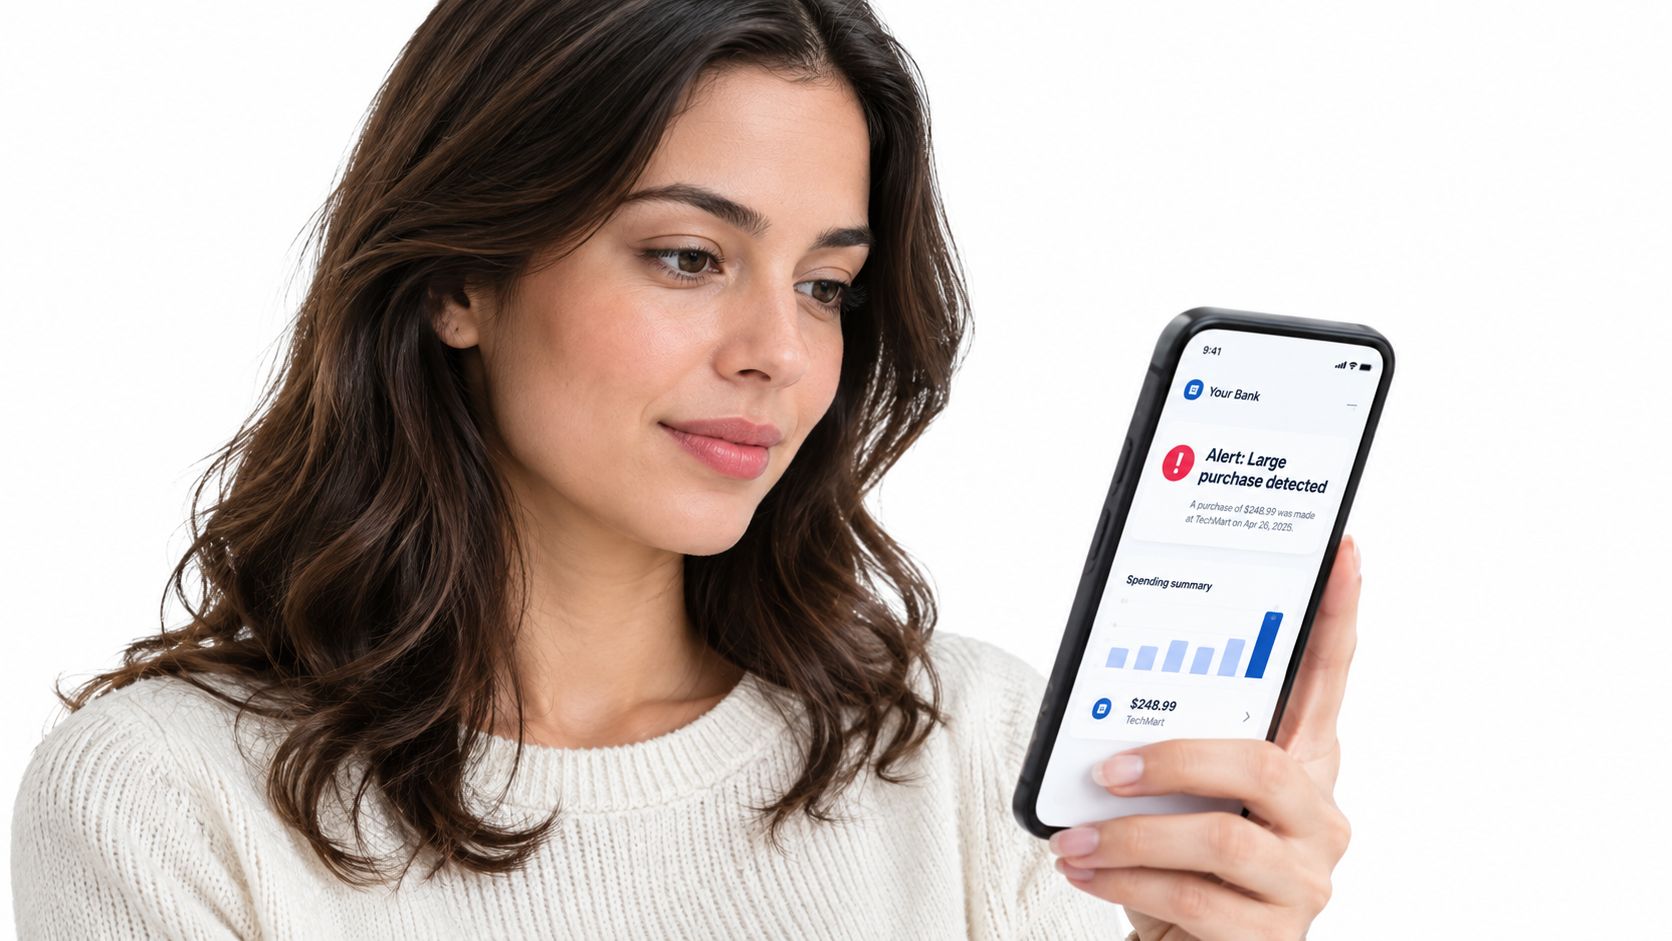
A quarterly statement rarely explains why a number matters, but video automation for banks can turn account data into a timely customer conversation. A retail bank connects its core system, CRM, and product database to a governed template that renders a short account update for each customer, without manual editing.
The message might use the customer’s name, account type, current balance, relevant spending activity, and an approved offer. A customer with a milestone balance could see a savings suggestion, while someone after a large purchase might receive a clear explanation of available alerts or payment options.
Turn Routine Updates Into Useful Moments
Static statements often leave customers to interpret fees, spending patterns, or product eligibility alone. A context-aware recorded message can highlight one or two relevant points with concise scenes, labels, narration, and a fixed call to action.
The practical shift is from asking customers to search a document for meaning to showing them the meaning behind their numbers.
Imagine a retail bank sending personalized account summaries each quarter instead of a generic email announcing that a statement is ready. Maria receives a greeting with her name, checking account type, recent activity category, balance movement, and an approved savings feature. Another customer receives a different version because their account, activity, and eligibility fields differ.
This makes retention communication more useful without requiring relationship managers to prepare thousands of messages individually. It can also support sales enablement, since relevant offers appear beside financial context rather than arriving as unrelated promotions.
Build Trust With Governed Data
The template should behave like a controlled form, not a blank script. Compliance teams approve the wording, disclosures, visuals, branding, and permitted fields before deployment, while the workflow accepts only validated values from authorised systems.
A bank can restrict inputs to:
- Identity: name and approved greeting.
- Account context: checking, savings, card, or loan type.
- Relevant activity: deposit, transfer, purchase category, or balance milestone.
- Eligibility: product or service approved for that customer segment.
- Next action: enable alerts, review a feature, or contact support.
That structure keeps every generated asset consistent and auditable. It also supports security reviews, version control, delivery records, and response tracking, which matter in a regulated industry. Guidance on banking automation similarly stresses that reliable workflows depend on accurate, connected data, as described in bank automation research.
A bank could begin with quarterly summaries, compare viewing completion, click-throughs, product uptake, and support contacts, then extend the same model to transaction alerts, lifecycle messages, employee training, and stakeholder updates.
For teams facing the problem of producing thousands of account-specific updates, a platform such as Wideo’s video automation solution can connect a data source to a template, trigger rendering after an approved account event, and distribute the finished asset through permitted channels.
When customers can see their financial story clearly, routine reporting becomes a reason to stay engaged.
Fraud alerts, loan offers, and staff training all suffer when banks rely on static messages that customers and employees skim.
Turn Alerts Into Reassuring Guidance
A fraud warning can feel alarming when it arrives as a short text with no context. With video automation for banks, the institution can create a brief, data-driven alert using the customer’s name, card type, transaction amount, merchant category, and the approved action, such as confirming or blocking the payment.
A clear recorded message can explain what happened without adding unnecessary friction.
The same workflow supports loan communication. A borrower might receive an audiovisual piece showing their loan type, repayment milestone, and an eligible refinancing option, while fixed disclosures and contact details remain unchanged. That gives sales teams a useful conversation starter without asking them to prepare individual assets.
Support Operations Beyond Customer Messages
Internal teams can receive dynamic training based on role, branch, or process. For example, a bank could send tellers a short module about a new identity-check procedure, while lending staff receive a different version covering updated documentation requirements.
The format also suits stakeholder reporting. A regional manager could receive a monthly summary showing branch name, service volume, complaint category, and approved performance indicators. Instead of assembling slides manually, operations teams use one repeatable template with validated inputs.
Practical applications include:
- Fraud response: Explain suspicious activity and the next approved step.
- Product promotion: Present eligible offers beside relevant account context.
- Employee training: Deliver role-specific process guidance.
- Reporting: Turn recurring metrics into clear management updates.
A retail bank might send personalized quarterly account summaries rather than a generic statement email. Maria’s version could show her checking account, recent spending category, balance movement, and an approved savings offer. Another customer would see different fields based on account type and eligibility.
Banks can map these values from core systems, CRM records, and product databases. A governed template then renders each message and sends it through email, mobile notifications, or a secure portal.
Teams exploring broader applications can review Wideo’s banking and business use cases before selecting a pilot. The essential principle remains simple: one approved structure, many relevant customer messages, and fewer manual handoffs.
When every department uses the same controlled workflow, communication becomes clearer, faster, and easier to measure. A bank’s most useful message may be the one that explains a number before the customer has to ask about it.
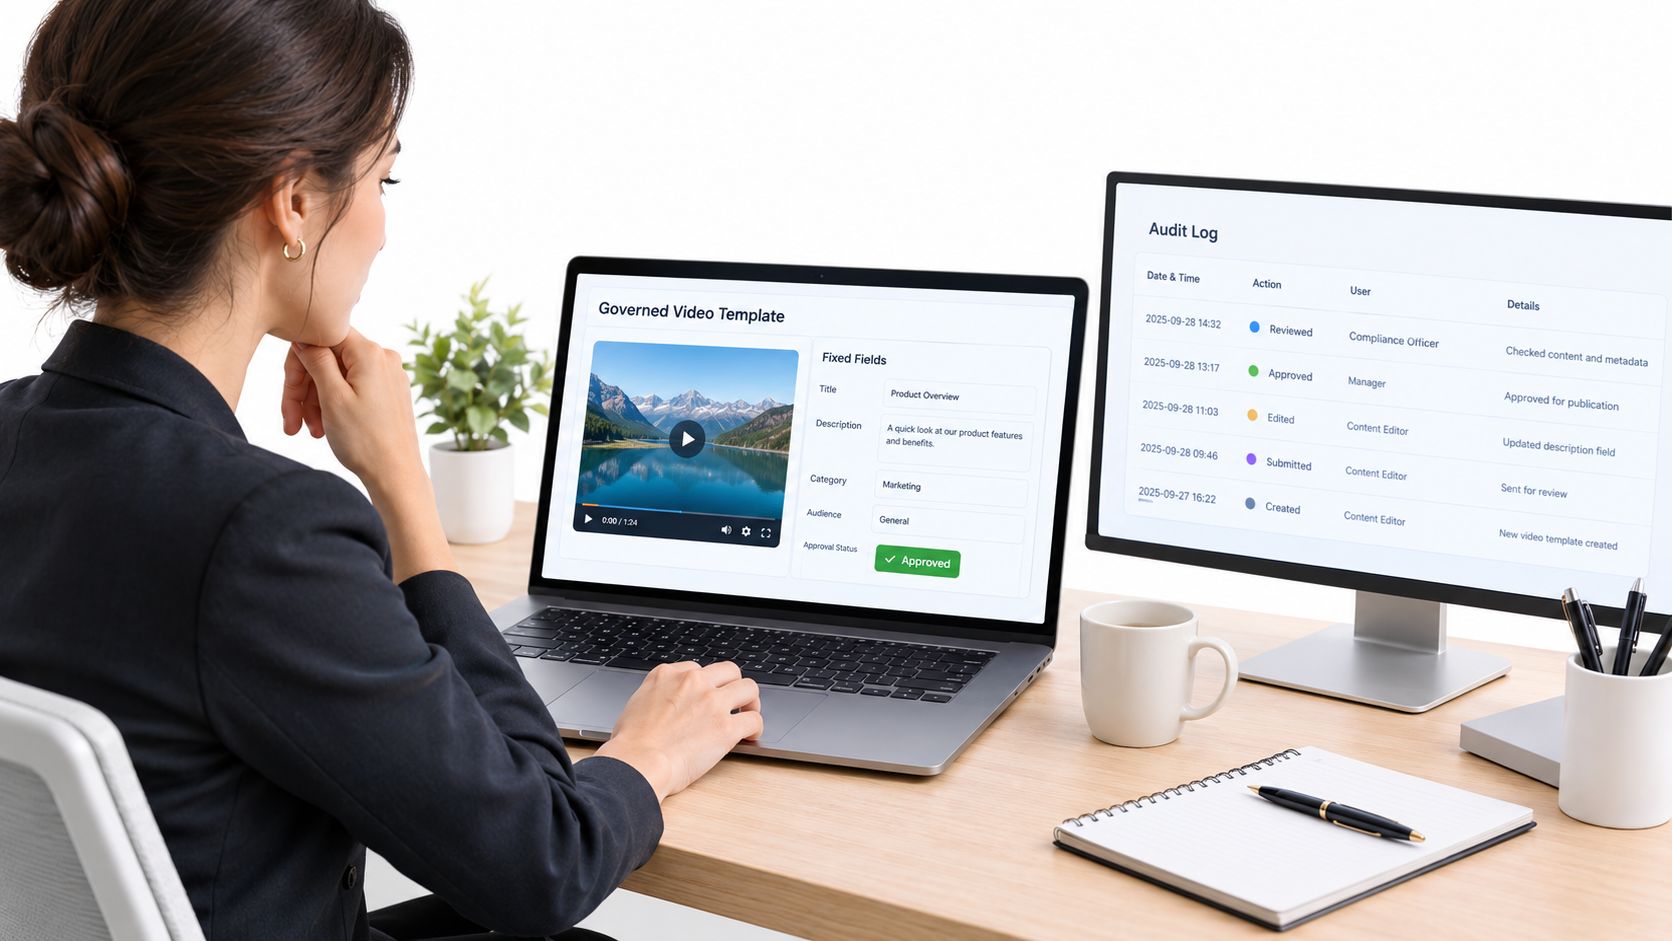
For banks, video automation has to start with governance, not creative production. A compliance team should sign off on the script, visuals, disclosures, branding, and permitted variables before a single customer message gets rendered.
Control Every Data Field
Think of the template as a locked form rather than a blank canvas. The workflow can accept a customer’s name, account type, relevant transaction category, balance movement, or product eligibility, but it can’t invent language or pull unauthorized information.
A retail bank sending quarterly account summaries could show Maria’s checking account, her recent spending category, the balance change, and an approved savings offer. Another customer sees different values, while the structure and regulatory wording stay identical.
Personalization changes the data, not the rules.
Compliance teams can also set thresholds, exclusions, and mandatory disclosures. Sensitive transaction details might be omitted, while every approved message follows the same visual and legal framework.
Preserve an Audit Trail
Each generated asset should link to a record of the source data, template version, approval status, rendering event, delivery channel, and customer response. That trail helps compliance officers investigate exceptions and demonstrate process control during internal or regulatory reviews.
Security reviews should cover access permissions, retention periods, encryption practices, and integration points with core banking and CRM systems. Banks also need to confirm that only authorized staff can edit templates or change field mappings.
For a practical reference, read Wideo’s privacy policy and data-handling information. The platform choice matters, but governance stays a bank responsibility.
A safe pilot can start with low-risk account summaries before expanding into transaction alerts, product promotions, employee training, or stakeholder reporting. The strongest banking workflow isn’t the one that creates the most assets, but the one that makes every asset explainable, approved, and traceable.
A bank doesn’t need to overhaul every customer communication process to start using video automation. The smartest approach is a focused pilot — something like welcome sequences or account summaries — where the value to customers is obvious and the data exposure stays contained.
Early churn in banking is brutal. Rates can climb past 20%, with almost half of new customers gone within the first 90 days. That makes onboarding the perfect place to test context-aware communication. Read more about early banking churn and video banking findings.
Start With a Controlled Pilot
Pick a narrow segment — say, new checking-account customers — and swap out a generic statement email for a short account summary video. The template pulls in the customer’s name, account type, opening date, recent transaction activity, current balance, and one pre-approved product offer, each mapped to a fixed scene.
The data changes for each customer, but the approved communication structure does not.
This setup lets you measure what actually shifts: viewing completion rates, support contact volume, account activation, and offer response, all benchmarked against the existing email flow. Before committing to an integration model, it also helps to learn how no-code video automation workflows work so the team knows what’s realistic.
Connect Data and Distribution
The workflow itself is straightforward. Core banking or CRM data feeds into approved template variables, an event triggers rendering, and the finished video lands in front of the customer through email, SMS, mobile push, or a secure portal.
Compliance needs to sign off on the script, disclosures, field mappings, branding, and exclusion rules before anything goes live. After that, access controls, template versioning, delivery logs, and retention policies create the audit trail regulators expect.
In practice, a platform like Wideo can sit between your CRM or account-data source and your distribution channels. It connects to a governed template, triggers generation after a statement cycle or onboarding event, and pushes the result through whichever channel you’ve approved. The platform handles production; your team keeps control of data permissions, review rules, and delivery policies.
Once the pilot proves reliable, the same workflow extends naturally to transaction alerts, product promotions, employee training, and internal management updates. Pick one measurable customer journey, prove the value, then grow your video automation program through governed, repeatable workflows.
Banks need more than viewing data to justify video automation for banks. The strongest evidence connects each personalized account summary with business outcomes, such as fewer support calls, greater product uptake, and stronger customer satisfaction.
Track Outcomes That Matter
A retail bank sending quarterly account summaries can compare customers receiving a dynamic asset with those receiving a generic statement email. Useful measures include:
- Completion rate: whether customers watch the summary through its final scene.
- Support demand: changes in calls about balances, fees, or transactions.
- Product response: clicks, applications, and funded accounts from approved offers.
- Customer sentiment: changes in Net Promoter Score after delivery.
A customer who watches an explanation of a balance change may not need to contact support. Another may notice an eligible savings product because the offer appears beside relevant account activity, rather than in a separate campaign.
Engagement shows attention, but reduced friction and increased action show business impact.
Test and Prove ROI
Banks should run controlled A/B tests without changing approved disclosures or permitted data fields. One group might receive a concise account summary, while another sees the same information with a different opening scene or call to action.
The bank can then compare completion, click-through, support contacts, applications, and NPS across both groups. For practical guidance, read this guide to measuring marketing video success.
A simple workflow connects account data to a governed template, triggers rendering after the quarterly statement event, and distributes the result through email, app notification, or a secure portal. When banks measure customer action alongside attention, video automation becomes a defensible operating investment rather than another communication expense.
Yes, video automation for banks can absolutely be done without exposing sensitive customer information. The trick is keeping tight control over what gets pulled into each video. You simply define the approved inputs—first name, account type, spending category, balance movement, product eligibility—and nothing else touches the workflow. From there, your compliance team reviews and signs off on the script, visuals, disclosures, and template version before anything goes out the door.
Does It Work With Legacy Banking Systems?
You don’t have to rip out your core platform. Plenty of banks run decade-old CRM and account databases just fine, and this approach plays nicely with that reality. Those existing systems feed validated values into an approved integration layer, while a visual template controls exactly how each piece shows up in the final video.
Here’s a concrete example. Imagine a retail bank ditching generic statement emails and sending quarterly account summaries instead. Maria’s personalized message pulls up her checking account, highlights her recent spending category, displays her balance change, and surfaces an approved savings offer—all without a human touching the file.
The data changes for each customer, but the communication rules stay locked in place.
Do You Need Professional Equipment?
Not at all. There’s no reason to book actors, rent studios, or buy expensive production gear. A clean script, brand-approved graphics, a professional voiceover, and your account data are plenty to put together something that actually works.
And once you’ve built that first template, the same structure supports customer onboarding, transaction alerts, product education, employee training, even internal reporting. Your team spends their time reviewing content and permissions rather than manually editing thousands of individual files.
How Long Does Implementation Take?
A focused pilot can kick off in weeks, not months. Pick one customer journey to start with—quarterly account summaries or welcome messages tend to be good candidates. The workflow connects a data source to a template, sets an approved trigger event, renders the message, and pushes it out through email, app notification, or a secure portal.
Teams drowning in manual video production should take a look at Wideo’s video automation platform as one practical workflow layer worth evaluating. Start with one governed use case, measure customer response and support volume, then expand from there.
Related posts:
 Your Store Isn’t Just a Store: It’s a Marketing Channel
 Video Marketing for Small Businesses A Complete Guide
 How Personalized Videos for Customers Forge Unbreakable Brand Loyalty
 Create a Presentation with Animation That Captivates and Persuades
 Scale Your Content Creation with Animated Video Templates
 12 Best Animation Software for Beginners in 2025


